
The Single Supervisory Mechanism is scheduled to deliver its annual evaluation findings to Greek banks on November 19 following an extensive balance sheet review.
The formal communication marks the final stage of the Supervisory Review and Evaluation Process, known as SREP. The procedure represents one of the most critical annual milestones conducted by the European banking supervisor, establishing an overall health check for each financial institution while setting regulatory requirements and operational expectations for the coming year.
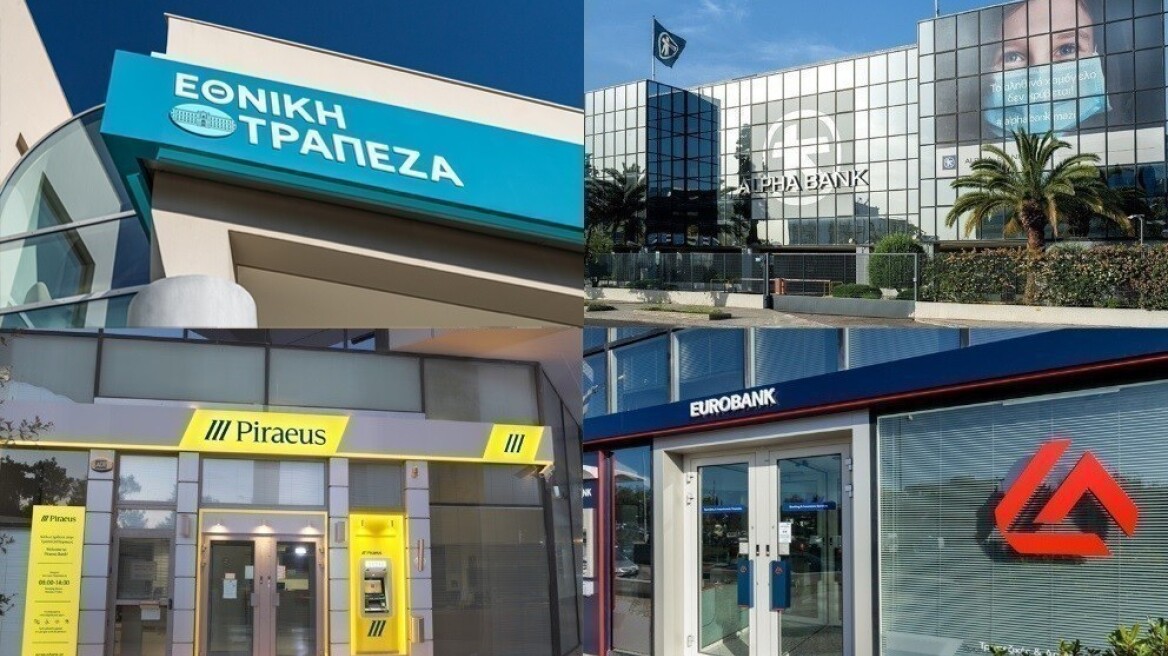
Supervisors have placed Greek lenders under heightened scrutiny this year, looking closely at commercial loans, shipping portfolios, bond holdings, and capital adequacy. Regulatory teams are also examining dividend distribution plans, deferred tax assets, liquidity reserves, and the broader resilience of bank balance sheets.
Focus on Emerging Balance Sheet Risks
According to reporting by Greek financial journalist Eirini Sakellari, European regulators are looking beyond the sector's current financial rebound. Greek credit institutions have achieved solid profitability, maintained robust capital positions, and made significant progress in cleaning up non-performing exposures over recent years.
However, the supervisory authority is seeking to identify emerging pockets of vulnerability that could erode asset quality over the medium term. The review comes against a backdrop of shifting economic conditions, rising financing requirements among corporations, and rapid credit expansion that is introducing fresh exposures across domestic loan books.
The European Supervisory Review Framework
The Single Supervisory Mechanism operates as the prudential supervision arm of the European Central Bank, overseeing systemically significant credit institutions across the euro area. The Frankfurt-based regulator conducts the SREP cycle annually to assess four core dimensions: business model viability, governance and risk controls, risks to capital, and risks to liquidity and funding.
Following the assessment, the supervisor assigns individual risk scores that determine mandatory capital buffers, known as Pillar 2 requirements, which banks must hold in addition to standard regulatory minimums. The supervisor also issues binding qualitative instructions addressing risk management weaknesses, compliance controls, and underwriting standards.
Scrutiny on Capital, Shipping, and Dividends
Several distinct areas of Greek banking operations are facing dedicated regulatory focus during this cycle. Shipping finance represents a historic area of concentration for Greek commercial lenders, requiring specialized credit assessment due to the cyclical swings of global trade and freight rates.
Capital composition remains another vital focal point for European authorities. Greek bank balance sheets continue to hold substantial amounts of deferred tax assets, which were accumulated during balance sheet restructuring after the sovereign debt crisis. Regulators examine the proportion of high-quality tangible equity against these tax credits when assessing whether lenders can safely proceed with planned dividend payouts to shareholders.
The final observations delivered on November 19 will set the supervisory agenda for Greek lenders, defining the capital cushions they must maintain and the risk safeguards required across their lending operations.